Explore potential car finance repayments with our Car Loan Repayment Calculator. Test different loan amounts, interest rates and repayment periods, and view detailed amortisation charts to see how repayments, interest costs and loan balances may change over time.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit.
Car Loan Details:
Important!
Car Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Loan Amortisation Calculator
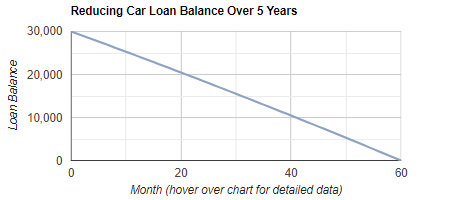
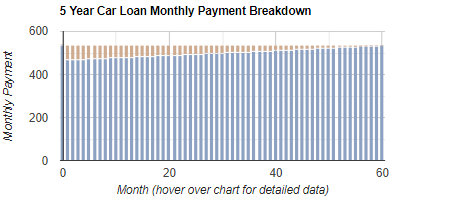
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Car Loan Repayment Calculator
Our Car Loan Repayment Calculator helps you estimate repayments for an Australian car loan and see how your balance, interest and principal change over time. It is important because small changes to the loan amount, term or interest rate can materially affect your monthly budget and the total interest you pay. The amortisation charts make it easier to compare scenarios and choose a structure you can afford with confidence.
General information only: This calculator provides an estimate and does not take into account your objectives, financial situation or needs. Results are indicative and your actual interest rate and repayments will depend on the lender, your credit profile and the final loan contract (including fees and conditions).
How to complete each section for the best result:
1. Purchase Price
Enter the vehicle purchase price as a whole number (no decimals or commas). If you plan to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts here so the estimate better reflects your likely loan size.
2. Deposit or Trade-in Value
Enter your cash deposit and/or trade-in value as a whole number. A higher deposit reduces the amount financed and usually lowers repayments and total interest.
3. Term of Loan (Years)
Select the number of years you want to repay the loan over. Shorter terms usually mean higher repayments but lower total interest. Longer terms can reduce monthly repayments but typically increase total interest paid.
4. Interest Rate (% per annum)
Select an interest rate to simulate. If you have a quote, choose the closest rate. If comparing options, run multiple calculations to see the impact of different rates.
5. Calculate
Click calculate to generate your results and charts.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability, leaving buffer for running costs and rate changes.
2. Amortisation charts: One chart shows the loan balance reducing over time; the other shows how early repayments are often interest-heavy and gradually shift toward principal repayment.
3. Comparison planning: Re-run the calculator with different terms, deposits and rates to identify a repayment level and total interest outcome that suits your budget.
Personal and commercial car loans can look similar, but they are assessed and structured differently. This guide explains how loan purpose, vehicle use, documentation, tax considerations and borrower obligations may differ in Australia. - read more
Self-employed Australians may be able to apply for a car loan without standard payslips, but a low doc car loan still requires evidence that income is reliable and repayments are affordable. This guide explains how low documentation vehicle finance works, what alternative income documents may be accepted, and what trade-offs borrowers should consider. - read more
Before signing a car loan contract in Australia, it helps to understand how responsible lending, credit contracts, hardship assistance, default notices and repossession risk may affect you as a borrower. - read more
Buying a new vehicle is an exciting experience, but finding budget-friendly car insurance can often feel overwhelming. Understanding how to navigate the landscape of car insurance is crucial to ensuring you get the best deal possible. - read more
Buying a car involves more than the purchase price. Before you choose a vehicle or arrange finance, it helps to understand ownership costs, borrowing limits, loan terms, reliability, depreciation and the checks that matter before you commit. - read more
Welcome to The Ultimate Guide to Fast Track Your Car Loan in Australia, designed to help you navigate the exciting journey of buying a car for the first time. Buying a car is a significant milestone, and securing the right finance can make all the difference. - read more
Australian car buyers are still committing to vehicle finance, but the latest lending figures suggest they are doing so with more caution. The Australian Bureau of Statistics September quarter 2026 Lending Indicators show new personal fixed-term loan commitments for road vehicles reached about $4.8 billion, up 1.8% from the June quarter, while sitting 2.7% lower than a year earlier. - read more
Australian car buyers have a fresh reason to revisit their finance assumptions after the Reserve Bank of Australia lifted the cash rate target by 0.25 percentage points to 4.85% on 3 November 2026. The move follows September’s increase and confirms that vehicle finance decisions are being made in a tougher interest-rate environment than many households and small businesses faced earlier in the year. - read more
Australian car buyers are heading into the final months of 2026 with a tougher interest-rate backdrop after the Reserve Bank of Australia lifted the cash rate target by 0.25 percentage points, taking it to 4.60% from 30 September 2026. For households and small businesses weighing up a new vehicle, the decision is a reminder that the cost of finance can shift even when the advertised price of a car looks stable. - read more
Recent comparison-market updates suggest Australian car buyers are entering spring with more choice, but not necessarily a simpler decision. Some lenders continue to advertise sharp secured car loan rates, particularly for borrowers with strong credit profiles and newer vehicles. Yet the gap between an appealing headline rate and the amount a borrower actually pays over the life of the loan remains a major issue for households and small businesses planning their next vehicle purchase. - read more
The Australian Taxation Office’s tax-time focus on work-related car expenses is a timely reminder that buying a vehicle for business use is not only a dealership decision. For self-employed Australians, contractors and small business owners, the way a car is used, financed and documented can shape both cash flow and tax record keeping long after the keys are handed over. - read more
Green car loan discounts are becoming a more important part of the vehicle finance conversation as Australian buyers weigh up electric vehicles, plug-in hybrids and fuel-efficient models. Recent comparison market updates show that some lenders continue to position lower-emission vehicles as a preferred segment, with sharper advertised rates or tailored products for eligible cars. - read more
Australia's new-vehicle market is continuing to shift, with the latest industry sales updates pointing to stronger interest in hybrids and plug-in hybrids alongside ongoing demand for electric vehicles. For car loan shoppers, the change is not just about what sits in the driveway. It can influence purchase price, running costs, expected resale value and the way lenders assess the vehicle being financed. - read more
Personal Loan: A Personal Loan is a means of obtaining finance from a financial institution or financial product provider and the lending criteria usually depends on criteria such as personal income and expenses, assets and liabilities, employment status and previo