The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Personal and commercial car loans can look similar, but they are assessed and structured differently. This guide explains how loan purpose, vehicle use, documentation, tax considerations and borrower obligations may differ in Australia.
Choosing between a personal car loan and a commercial car loan is not just a matter of labelling the application differently. In Australia, the right loan purpose usually depends on how the vehicle will be used, who is borrowing, how income is verified and whether the vehicle is connected to business activity.
If you are comparing personal and commercial car loan options, it helps to understand the practical differences before you apply. This guide explains how personal car loans and commercial car loans generally differ, what lenders may look for and what questions to ask before deciding which path fits your situation.
What is the main difference between a personal and commercial car loan?
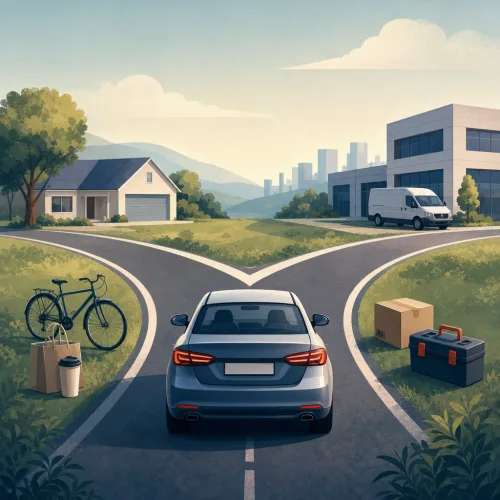
The main difference is the purpose of the vehicle and the borrower's situation. A personal car loan is generally used when the vehicle is mainly for private use, such as commuting, family transport or personal travel. A commercial car loan is generally used when the vehicle is primarily for business use, such as visiting clients, carrying tools, making deliveries or operating as part of a business fleet.
The distinction matters because lenders may assess the application under different criteria, request different documents and offer different loan structures. Tax and accounting treatment may also differ depending on the borrower, business structure and actual vehicle use.
This article provides general information only. It does not consider your personal objectives, financial situation or needs. For tax, legal or accounting questions, consider speaking with a qualified adviser or accountant.
How personal car loans usually work
A personal car loan is commonly used by an individual buying a vehicle for private use. The borrower is usually assessed on their personal income, expenses, existing debts, credit history and ability to meet repayments.
Personal car loans may be secured or unsecured. With a secured personal car loan, the vehicle is typically used as security for the loan. This means the lender may have rights over the vehicle if the borrower defaults, subject to the loan contract and relevant law. With an unsecured personal loan used to buy a car, the lender does not take the vehicle as security, but the rate and eligibility criteria may differ.
Common examples of personal use include:
- driving to and from work;
- school drop-offs and family transport;
- weekend and holiday travel;
- buying a first car or upgrading a household vehicle;
- occasional incidental work-related use where the vehicle is still mainly private.
Because the loan is for personal use, lenders generally focus on the individual borrower's personal financial position. They may ask for payslips, bank statements, identification, details of debts and living expenses, and information about the vehicle being purchased.
How commercial car loans usually work
A commercial car loan is designed for a vehicle used mainly for business purposes. Depending on the lender and structure, it may be offered to a sole trader, partnership, company, trust or another business entity. In Australia, commercial vehicle finance is often associated with structures such as a chattel mortgage, finance lease or business vehicle loan, although product names and terms vary between providers.
Commercial car finance may suit situations such as:
- a sole trader buying a ute for tools and site visits;
- a small business purchasing a delivery van;
- a company acquiring vehicles for employees;
- a rideshare, courier or trade business financing a work vehicle;
- a business replacing or expanding its vehicle fleet.
For a commercial car loan, the lender may consider both the borrower's financial position and the business's ability to support the repayments. This can involve reviewing business income, cash flow, trading history, tax documents, bank statements and the vehicle's role in the business.
Commercial loans may also involve different protections and obligations from consumer loans. If a loan is wholly or predominantly for business purposes, it may not be regulated in the same way as a consumer credit contract. Borrowers should read the contract carefully and ask questions before signing.
Personal vs commercial car loan Australia: side-by-side comparison
| Feature |
Personal car loan |
Commercial car loan |
| Main purpose |
Vehicle mainly used for private or household purposes. |
Vehicle mainly used for business or income-producing activity. |
| Typical borrower |
Individual consumer. |
Sole trader, company, partnership, trust or business owner. |
| Assessment focus |
Personal income, expenses, credit history and debt commitments. |
Business income, cash flow, trading history, credit profile and vehicle purpose. |
| Common documents |
Identification, payslips, bank statements, debt details and vehicle information. |
ABN or business details, financials, tax documents, business bank statements and vehicle information. |
| Loan structures |
Secured car loan or unsecured personal loan. |
Business vehicle loan, chattel mortgage, lease or other commercial finance structure. |
| Tax considerations |
Generally no business tax treatment unless eligible work-related use applies. |
Business-use deductions, GST and depreciation may be relevant depending on circumstances. |
| Consumer protections |
May be covered by consumer credit laws where the loan is for personal, domestic or household use. |
May have different protections if the loan is for business purposes. |
How vehicle use affects the loan purpose
Vehicle use is one of the most important factors. A lender may ask whether the car will be used for private use, business use or a mix of both. The answer should reflect the real purpose of the vehicle, not simply the loan type you prefer.
Mixed-use vehicles can be more complex. For example, a sole trader may use one vehicle for client visits during the week and family errands on weekends. In that case, the lender may need to understand whether business use is the primary purpose. Your accountant may also need to consider how business and private use are recorded for tax purposes.
It is important to be accurate. Misstating the purpose of the loan can create problems with the lender, the loan contract, insurance, tax reporting and future disputes.
Documentation: what lenders may ask for
Documentation varies by lender, loan amount, vehicle type, credit profile and applicant circumstances. However, personal and commercial applications often differ in the kind of evidence required.
Personal car loan documents
For a personal car loan, lenders may request:
- proof of identity;
- recent payslips or other income evidence;
- bank statements;
- details of rent, mortgage payments and living expenses;
- details of existing loans, credit cards and other debts;
- information about the vehicle, such as price, age, condition and seller details.
Commercial car loan documents
For a commercial car loan, lenders may ask for some personal information as well as business-related documents, such as:
- ABN and business registration details;
- business bank statements;
- tax returns, financial statements or accountant-prepared documents;
- BAS or other evidence of turnover, where relevant;
- details of business debts and assets;
- information about how the vehicle will be used in the business.
Some lenders may offer low-doc or alternative-documentation options for self-employed applicants, but availability and terms depend on lender criteria and the strength of the application.
Tax and accounting considerations
Tax treatment is often one of the reasons business owners consider commercial car finance. Depending on your circumstances, business vehicle costs may involve considerations such as interest deductions, depreciation, GST credits, running expenses and private-use adjustments.
However, tax outcomes are not automatic. They can depend on factors such as:
- who owns or leases the vehicle;
- the business structure;
- the percentage of business versus private use;
- whether the vehicle is available for employee or personal use;
- the finance structure chosen;
- ATO rules and record-keeping requirements that apply at the time.
Do not choose a commercial car loan purely because you expect a tax benefit. Speak with an accountant or registered tax adviser before relying on any tax treatment, especially if the vehicle has mixed personal and business use.
Interest rates, fees and loan terms can differ
Neither personal nor commercial car finance is automatically cheaper or more suitable. Rates, fees and terms depend on the lender, borrower profile, credit history, vehicle, loan amount, deposit, loan term and whether the loan is secured.
Commercial finance may allow features that suit business cash flow, such as structured repayments or a balloon amount at the end of the term. A balloon can reduce regular repayments during the loan, but it leaves a larger final amount to pay, refinance or manage at the end. This can affect total cost and should be considered carefully.
Before applying, it can be useful to estimate repayments with a car loan calculator. Calculators are only a guide, but they can help you compare different loan amounts, terms and repayment assumptions before speaking with a lender or broker.
Which option may suit different borrowers?
The right option depends on the genuine purpose of the vehicle and how the loan will be assessed. The following examples are general only.
- Employee buying a family car: A personal car loan will often be the more relevant category if the vehicle is mainly for household or commuting use.
- Sole trader buying a ute for jobs: A commercial car loan may be relevant if the vehicle is mainly used to earn business income.
- Company buying a delivery van: Commercial finance is likely to be considered because the borrower and vehicle purpose are business-related.
- Self-employed person using one car for work and family: The correct loan purpose may depend on the dominant use, lender criteria and tax treatment. Record-keeping may be especially important.
- Employee with some work travel: Occasional reimbursed work travel does not necessarily make the vehicle a business vehicle for finance purposes.
Questions to ask before you apply
Before choosing between a personal car loan and a commercial car loan, consider asking:
- Will the vehicle be used mainly for private or business purposes?
- Who should be the borrower: an individual, sole trader, company or another entity?
- What documents will the lender require?
- Will the loan be secured against the vehicle?
- What are the fees, repayment options and early payout conditions?
- Is there a balloon payment or residual value, and what happens at the end of the term?
- How will business and private use be recorded?
- Should an accountant review the tax implications before applying?
- Does the loan contract include consumer credit protections, or is it a business-purpose contract?
If you are unsure how a lender may view your situation, speaking with a car finance broker may help you understand what information different lenders commonly request. Any approval, pricing or available loan terms will still depend on your circumstances and lender criteria.
Common mistakes to avoid
- Choosing the loan type based only on rate: A lower advertised rate does not necessarily mean a lower total cost or better fit for your circumstances.
- Misstating the vehicle purpose: The application should accurately reflect how the car will be used.
- Ignoring tax advice: Business vehicle finance can have tax and GST implications that should be checked with a qualified adviser.
- Overlooking total ownership costs: Registration, insurance, fuel, servicing, tyres and repairs can affect affordability.
- Not comparing loan structures: A secured loan, unsecured loan, chattel mortgage or lease can each affect ownership, repayments and end-of-term obligations differently.
- Assuming business finance is easier: Commercial lenders still assess risk, cash flow, credit history and vehicle suitability.
Final thoughts
A personal car loan is generally for a vehicle used mainly for private purposes, while a commercial car loan is generally for a vehicle used mainly for business purposes. The difference can affect assessment criteria, documentation, loan structure, tax considerations and borrower obligations.
Before applying, be clear about how the vehicle will be used, compare the total cost of finance and seek professional advice where tax or business-structure questions are involved. A well-matched loan purpose can make the application process clearer and reduce the risk of problems later.
Published: Saturday, 1st Aug 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.